Comprehending Your Obligations to Multiple Creditors
What Strategies Can You Use to Effectively Identify Your Creditors?
To grasp your financial commitments thoroughly, you must undertake a meticulous review of all your agreements. Begin by creating a comprehensive list of every creditor to whom you owe money, noting the outstanding balances. Pay close attention to the interest rates and repayment terms specific to the UK, as these elements greatly impact your approach to managing your debt.
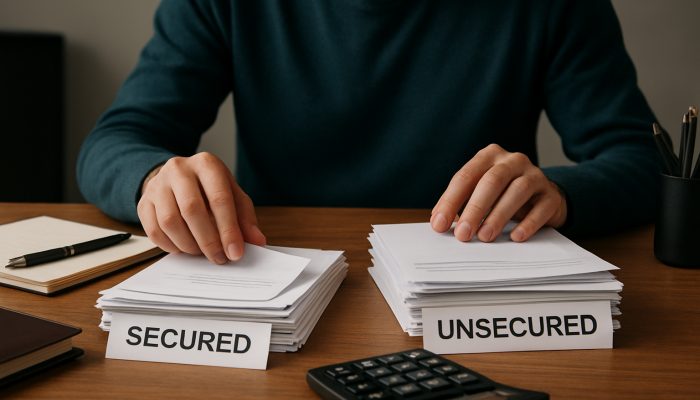
After compiling your list, categorise each creditor according to the nature of the debt—secured or unsecured. This classification will enable you to prioritise repayments and identify which debts require immediate attention versus those that can be managed over time. Gaining insight into your creditors is a crucial step towards regaining control over your financial situation.
How Can You Accurately Assess Your Total Debt Levels?
Understanding your total debt levels is essential for evaluating your financial health. Start by calculating your monthly commitments across all accounts; this will give you a clearer picture of what you can manage financially. This assessment helps prevent you from stretching your resources too thin while ensuring compliance with local regulations.
Regularly reviewing your debt levels allows you to adjust your budget as needed. If your monthly obligations exceed your income, it may be prudent to consider debt consolidation or other financial strategies to regain control. Being aware of your total debt serves as the foundation for effective financial planning.
How Do You Identify Which Debts Should Be Prioritised?
Understanding the difference between secured loans and unsecured credit is vital for effective debt management. Secured loans, such as mortgages, are linked to specific assets, while unsecured debts, like credit cards, do not involve collateral. Here are some key advantages of recognising these distinctions:
- Secured loans typically offer lower interest rates.
- Defaulting on secured loans can lead to asset repossession.
- Unsecured debts often provide greater flexibility in repayment terms.
- Recognising priorities can aid in negotiations with creditors.
Understanding these differences allows you to create a repayment strategy that reduces risks and prioritises your financial wellbeing. This knowledge empowers you to make informed decisions about which debts to tackle first.
What Debt Consolidation Options Can You Explore?
Which Loan Options Should You Consider for Consolidation?
When contemplating debt consolidation, various loan options can simplify your financial commitments. Personal loans and balance transfer credit cards are popular choices, allowing you to merge multiple debts into a single payment, often at reduced interest rates. Residents in the UK can benefit from comparing these options to find the best fit for their unique circumstances.
It is crucial to thoroughly evaluate the terms of each consolidation option. Seek loans with no hidden charges and favourable repayment conditions. By consolidating your debts, you may lower your monthly payments and streamline your financial management, making it easier to keep track of your obligations.
What Eligibility Criteria Must You Meet for Consolidation?
Before applying for debt consolidation products, it is essential to understand the eligibility criteria set by UK financial institutions. Generally, lenders will assess your <a href=”https://www.debtconsolidationloans.co.uk/how-to-improve-your-credit-score-quickly/”>credit score</a>, income level, and current debt-to-income ratio. Understanding these requirements can help you prepare and enhance your chances of approval.
Some lenders may require a minimum income level or specific credit score to qualify for their products. It is advisable to check your credit report before applying, addressing any issues that could hinder your application. This preparation can save you time and improve your overall financial outlook.
How Can You Estimate Potential Savings from Debt Consolidation?
Calculating potential savings from debt consolidation is a wise step for UK borrowers managing multiple accounts. Online calculators can help you determine how much you could save in interest payments by consolidating your debts into a single loan with a lower interest rate.
By entering your current debts and interest rates into these calculators, you can visualise the financial benefits of consolidation. This process not only clarifies potential savings but also enables you to make informed decisions regarding your financial future. Understanding these figures can motivate you to take decisive action.
What Risks Should You Be Aware Of When Consolidating Debt?
While debt consolidation presents numerous advantages, it is crucial to evaluate the associated risks before committing to any options. One primary drawback could be setup fees, which may counteract the savings achieved through lower interest rates. Opting for a longer repayment period might also result in accruing more interest over time.
Another consideration is the potential impact of consolidation on your credit history. Although consolidating can improve your score by reducing credit utilisation, missing payments on the new loan could have serious repercussions. Weighing these risks against potential benefits is essential for making sound financial decisions.
Professional Guidance for Managing Responsibilities to Multiple Lenders
What Debt Relief Options Are Available to You?
In the UK, there are various options to provide relief when you owe money to multiple lenders. Debt management plans (DMPs) represent one such solution that adheres to Financial Conduct Authority standards. These plans allow you to repay your debts at a manageable rate, often negotiated with creditors to lower monthly payments.
Another alternative is an Individual Voluntary Arrangement (IVA), which facilitates a formal agreement with your creditors to repay a portion of your debts over a specified timeframe. Consulting with a financial advisor to explore these options can help you identify the best path to financial recovery while ensuring compliance with UK regulations.
How Can You Evaluate the Terms of Your Agreements?
Negotiating with creditors is a critical step in effectively managing multiple debts. Begin by reviewing the terms of your existing agreements and identifying areas where you might request adjustments, such as lower interest rates or extended repayment periods. This proactive approach can lead to more manageable payment plans.
During negotiations, ensure adherence to British consumer protection laws. Clearly articulate your case and be transparent about your financial circumstances. Many creditors are willing to cooperate if they recognise your commitment to repaying your debts. This open dialogue can facilitate the establishment of a more sustainable repayment plan.
What Real-Life Examples Can Inform Your Strategy?
Studying case studies of individuals who have successfully restructured their payments in accordance with UK guidelines can provide invaluable insights. For instance, an individual with multiple credit cards might have negotiated a DMP that halved their monthly payments, allowing them to manage their finances more effectively while avoiding bankruptcy.
Another example could feature someone who employed an IVA to consolidate debts, resulting in a structured repayment plan that alleviated the pressure of dealing with several creditors. These real-world scenarios underscore the significance of exploring available options and seeking professional guidance to achieve sustainable outcomes.
What Are the Consequences of Missing Payments?
How Do Missed Payments Affect Your Credit Scores?
Failing to make payments can significantly impact your credit score, which is reported to UK credit agencies. Even a single late payment can lower your rating, complicating future borrowing approvals. Over time, a poor credit score can lead to higher interest rates and less favourable loan terms.
To mitigate these risks, prioritise your payments and maintain open communication with your lenders if you foresee difficulties. Taking proactive measures can help protect your credit score and uphold your financial reputation, enabling you to manage your debts more effectively.
What Are the Potential Legal Consequences of Missed Payments?
Understanding the possible legal ramifications of missed payments is vital for anyone dealing with multiple creditors. In England and Wales, creditors may initiate court proceedings or engage bailiffs to recover debts. This process can escalate quickly and incur additional costs, making it essential to stay current on your repayments.
If you find yourself struggling to meet your obligations, consider seeking professional advice before the situation intensifies. Familiarising yourself with your rights and options can help you navigate this challenging landscape while minimising legal repercussions. Awareness of the legal framework surrounding debt recovery is crucial for informed decision-making.
How Does Interest Accumulate on Missed Payments?
Late fees can accumulate rapidly across multiple accounts, resulting in increased balances that strain household budgets in the UK. Each missed payment typically incurs additional interest, causing your overall debt to grow faster than expected. Understanding how interest accrues is essential for effectively managing your financial obligations.
To counteract this issue, establish a system for tracking payment due dates and ensure that you remain current on your obligations. By prioritising timely payments, you can minimise the impact of interest accumulation and maintain better control over your financial situation.
Practical Strategies for Managing Multiple Creditors
How Can You Prioritise Your Debt Repayments Effectively?
Focusing on the debts with the highest interest rates first is a proven strategy for managing multiple lenders. By targeting these debts, you can reduce the overall interest you pay, ultimately saving money in the long term. Making minimum payments on other debts ensures that you stay current while addressing the most costly obligations.
This prioritisation strategy requires careful budgeting and expense tracking. By developing a clear plan, you can systematically tackle your debts and work towards achieving financial freedom. Regularly reviewing your progress can help maintain your motivation and focus on your objectives.
How Can You Establish a Reliable Emergency Fund?
Consistently setting aside small amounts to build an emergency fund is a vital strategy for avoiding reliance on additional credit. This fund can cover unexpected expenses, enabling you to manage your financial obligations without resorting to high-interest loans. In the UK, even a modest emergency fund can provide significant peace of mind.
To create your emergency fund, consider automating transfers to a separate savings account. This method ensures consistent contributions without the temptation to spend the money elsewhere. Over time, small contributions can accumulate, creating a safety net for unforeseen costs.
What Real-Life Examples Validate This Approach?
Effective debt management often stems from learning from real-life experiences. For instance, a UK resident may have implemented a debt repayment plan that prioritised high-interest debts while simultaneously building an emergency fund. This strategy enabled them to reduce financial stress and ultimately pay off their debts more efficiently.
Another example might involve an individual who utilised budgeting tools to monitor their spending and identify areas for reduction, freeing up funds for debt repayment. These practical steps illustrate that, through careful planning and commitment, it is indeed possible to manage the pressures of multiple lenders effectively.
What Alternatives to Debt Consolidation Should You Consider?
Exploring debt consolidation options can simplify your financial management, particularly when dealing with multiple creditors. By consolidating several debts into a single loan with a lower interest rate, you can streamline your payments and alleviate the burden of managing various lenders. This approach can yield improved financial outcomes over time.
When considering debt consolidation, it is vital to research various lenders and their offerings. Look for loans that are free of hidden charges and come with favourable terms. A well-structured consolidation loan can provide relief and make it easier to stay on top of your repayments while regaining control over your finances.
Why Is Maintaining Open Communication with Creditors Crucial?
Regular contact with your creditors is essential for effective debt management. Informing them of your situation may lead to negotiations for temporary reductions in payments or alternative arrangements. Demonstrating good faith through open communication can foster a more cooperative relationship with your lenders.
Being proactive in your communications can help you navigate financial challenges more effectively. Creditors are generally more willing to work with individuals who are upfront about their difficulties. This approach can result in more manageable repayment plans and ultimately help you regain control over your financial situation.
What Does Seeking Professional Support Involve?
How Can You Access Debt Advice Services?
Obtaining free guidance from accredited UK charities that specialise in multi-lender scenarios can be invaluable. These organisations offer impartial advice and support tailored to your unique financial situation. Seeking their guidance can provide clarity and direction as you navigate your debt challenges.
Many of these services can assist you in developing a personalised debt management plan, ensuring that you take the appropriate steps towards financial recovery. They can also help negotiate with creditors, providing you with the confidence to manage your debts effectively. Professional guidance can be transformative on your path to financial stability.
What Should You Understand About Fee Structures?
Evaluating the costs associated with commercial debt firms regulated under British oversight is vital to ensuring value for money. Some firms may impose high fees that could diminish the benefits of their services. Understanding the fee structure enables you to make informed decisions regarding which services to engage.
Always request a clear breakdown of fees before committing to any debt management service. This transparency allows you to compare options and choose the best fit for your financial situation. Being well-informed can help you avoid unnecessary costs while seeking the assistance you require.
How Should You Prepare Your Financial Documentation?
Collecting statements and income details in advance can streamline discussions with advisors who are familiar with local laws. Having all relevant documents organised allows you to present your situation clearly, making it easier for advisors to provide tailored advice. This preparation can lead to more productive consultations.
Organising your financial documents also enhances your understanding of your situation. By reviewing your income and expenses, you can identify areas for improvement and be more proactive in discussions with advisors. This thorough preparation is key to achieving your financial goals.
What Actions Can You Take to Improve Your Financial Situation?
How Do You Create an Effective Budget Plan?
Meticulously tracking your expenses against your income is essential for establishing a budget plan that meets all lender requirements. A well-structured budget enables you to allocate funds appropriately, ensuring that you can manage your debts while covering essential living costs. Regularly reviewing your budget helps identify areas for potential savings.
By categorising your expenses, you can pinpoint areas where you may be overspending and make necessary adjustments. This proactive approach not only helps you stay on top of your repayments but also promotes a healthier financial lifestyle. A clear budget serves as the cornerstone of effective financial management.
Why Is Regular Monitoring of Progress Important?
Assessing your financial statements on a monthly basis is crucial for tracking your progress as you work towards reducing your debt. Regular evaluations allow you to adjust your plans as balances decrease, keeping you motivated throughout your repayment journey. Monitoring your progress provides a sense of achievement and helps you remain focused on your objectives.
By celebrating small victories along the way, you can maintain your motivation and commitment to your financial plan. This ongoing evaluation is vital for ensuring that you remain on track and can modify your strategy as needed. Staying engaged with your financial progress is key to long-term success.
What Are the Key Advantages of Sustaining Long-Term Financial Habits?
- Enhances financial literacy and awareness.
- Reduces reliance on credit for emergencies.
- Improves budgeting skills for better control.
- Encourages saving habits for future security.
- Fosters a healthier relationship with money.
- Promotes a proactive approach to financial challenges.
Establishing long-term habits to prevent future debt accumulation is essential for achieving financial stability. By integrating these practices into your daily routine, you can build a solid foundation for a more secure financial future.
Commonly Asked Questions
What Should Your First Step Be If You Owe Money to Multiple Creditors?
Start by compiling a list of all your creditors, outstanding balances, and interest rates. Understanding your financial obligations is crucial for formulating a repayment strategy.
Is It Easy to Consolidate Your Debts in the UK?
Yes, many UK lenders offer debt consolidation loans or balance transfer options. It is essential to compare rates and terms to find the best fit for your needs.
What Risks Are Associated with Debt Consolidation?
Debt consolidation may involve fees, and extending repayment terms can result in paying more interest over time. It is important to weigh the pros and cons before proceeding.
How Can You Improve Your Credit Score While Managing Debt?
Make timely payments, maintain low credit utilisation, and avoid incurring new debts. Regularly checking your credit report can also help you identify areas for improvement.
What Is a Debt Management Plan?
A debt management plan (DMP) is an agreement with creditors to pay off debts at a rate you can afford. It simplifies payments and can reduce financial stress.
How Can You Determine If You Need Professional Assistance?
If you are having difficulty managing your debts or feel overwhelmed, seeking professional advice from a financial advisor or charity can provide valuable guidance and support.
Are There Free Resources for Debt Advice in the UK?
Yes, organisations like Citizens Advice and StepChange offer free, impartial advice for individuals dealing with debt. They can assist in exploring your options and creating a plan.
What Are the Consequences of Missing a Payment?
Missing a payment can negatively impact your credit score and may lead to additional fees or legal action from creditors. It is essential to communicate with lenders if you expect difficulties.
Can You Negotiate with Your Creditors?
Yes, it is often possible to negotiate with creditors. Many are willing to work with you on payment terms if you explain your situation and demonstrate a commitment to repaying.
How Can You Build an Emergency Fund While Repaying Debts?
Start small by setting aside a portion of your income each month. Automating transfers to a separate savings account can help you build an emergency fund without relying on credit.
Visit Our Facebook Profile!
This Article Was First Found On: https://www.debtconsolidationloans.co.uk
The Article Debt Solutions for Owing Money to Multiple Lenders found first on https://electroquench.com